2025 US Income Tax Guide: Brackets, Deductions, and Smart Planning Before 2026

🧾 The Essential Guide to US Income Tax (2025)
Structures, Strategies & Smart Planning Before 2026 Sunset
1. 📚 Introduction: How the US Income Tax System Works
The US tax system is progressive, meaning you pay a higher rate as your income rises. But it’s not just federal—most states also impose income taxes. In July 2025, the “One Big Beautiful Bill Act” reshaped the tax code with permanent changes to TCJA rates and added new deductions for workers, retirees, and homeowners.
⚠️ Why it matters: Many 2017 TCJA provisions will expire after 2025, so this is a pivotal year for strategic tax planning.
2. 🏛️ 2025 Federal Tax Brackets & Deductions
📌 A. Tax Brackets (2025) — Now Permanent
Thanks to the 2025 reforms, these brackets are locked in:
| Rate | Single Filers | Married Filing Jointly |
|---|---|---|
| 10% | $0 – $11,925 | $0 – $23,850 |
| 12% | $11,926 – $48,475 | $23,851 – $96,950 |
| 22% | $48,476 – $103,350 | $96,951 – $206,700 |
| 24% | $103,351 – $197,300 | $206,701 – $394,600 |
| 32% | $197,301 – $250,525 | $394,601 – $501,050 |
| 35% | $250,526 – $626,350 | $501,051 – $751,600 |
| 37% | Over $626,350 | Over $751,600 |
✅ Effective Tax Rate Tip: You’re taxed only the amount within each bracket, not your full income.
📌 B. Standard & Senior Deductions
2025 updates increased standard deductions:
- Single: $15,000
- Married Filing Jointly: $30,000
- Head of Household: $22,500
🌟 New 2025 Feature: Seniors (65+) can deduct an extra $6,000 per person, phased out at MAGI >$75,000 (single) or >$150,000 (joint).
3. 🔍 Major Tax Changes Under the 2025 Bill
✅ A. New Deductions for Workers
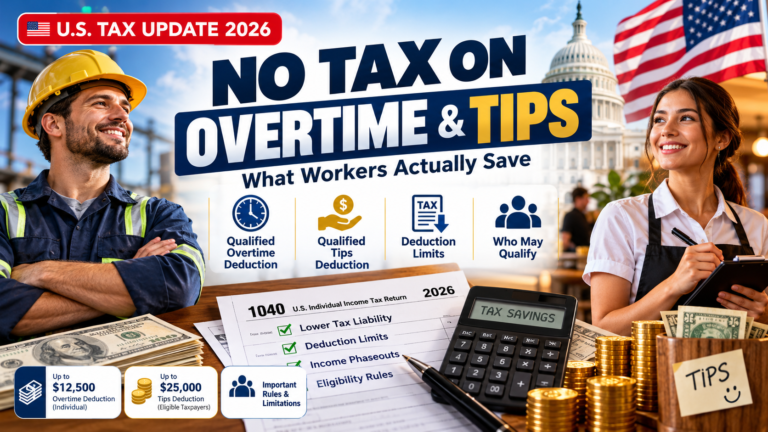
- 💸 Tip Income Deduction: 100% deductible up to $25,000 if reported on W-2/1099.
- ⏱️ Overtime Deduction: Deduct 50% of OT premiums (max: $12,500 single/$25,000 joint).
- 🚘 Auto Loan Interest: Deduct up to $10,000/year on new US-assembled vehicle loans.
🧠 Phaseouts apply — check if your MAGI exceeds limits.
✅ B. SALT Deduction Relief
The SALT (state and local taxes) cap increased:
- Joint Filers: $40,000 cap, phasing out at MAGI >$600,000
- Single Filers: $20,000 cap, phasing out at MAGI >$300,000
💡 Strategy: Prepay property taxes in high-income years.
✅ C. Estate & Gift Tax Updates
- Estate Exemption: $13.99M (2025); will drop to ~$7M in 2026.
- Gift Tax: Annual exclusion raised to $19,000.
⚠️ Act Now: Use the high exemption before it vanishes.
4. 🗺️ State Income Tax: Know Where You Stand
🧾 Types of State Income Tax Systems
- No Income Tax: FL, TX, NV, SD, WY, WA, TN, AK
- Flat Tax: e.g., Arizona (2.5%), North Carolina (4.99%)
- Progressive: CA (up to 13.3%), NY (up to 10.9%)
🔁 Residency Planning: High earners often relocate for savings.
5. 💰 Key Federal Credits & Deductions (2025)
💡 A. Tax Credits
- Child Tax Credit: $2,200 per child ($1,700 refundable)
- EITC: Max of $8,046 (3+ children)
- Adoption Credit: $17,280
💼 B. Savings & Retirement Tools
- 401(k): $23,500 (plus $7,500 catch-up)
- IRA: $7,000 (plus $1,000 catch-up)
- HSA: Deductibles increased by $50–$150
- FSA: Contribution cap now $3,300
✅ Deadline: You can fund IRAs for 2025 until April 15, 2026.
6. 🧠 Year-Round Tax Planning Tips
- Itemize Smartly: Mortgage interest, medical expenses, donations
- Harvest Losses: Offset gains with investment losses
- Maximize Contributions: Use SEP-IRAs and Solo 401(k)s (limit: $69,000)
- Quarterly Payments: Avoid penalties by paying estimated tax
📆 Rule: Pay at least 100% of last year’s tax (110% if AGI >$150,000)
7. 🔮 Preparing for the 2026 Sunset
When the TCJA expires, expect:
- 📈 Rates increase: Top rate rises to 39.6%
- 💰 Estate tax cuts: Exemption halves
- 🔻 SALT cap shrinks: Returns to $10,000
✅ 2025 Strategy Checklist
- ✔️ Realize capital gains now
- ✔️ Make large gifts while exemption is high
- ✔️ Convert IRAs to Roth accounts
- ✔️ Prepay SALT-heavy expenses
8. 🙋♂️ Frequently Asked Questions (FAQ)
🔹 What’s the difference between marginal and effective tax rate?
Marginal is the rate on your last dollar earned. Effective is the average you pay across all brackets.
🔹 Should I itemize or take the standard deduction?
Itemize only if deductions exceed your standard deduction. Homeowners often benefit from itemizing.
🔹 Can I deduct student loan interest in 2025?
Yes, up to $2,500, subject to income phaseouts (unchanged).
🔹 What’s the best retirement plan for freelancers?
A Solo 401(k) or SEP-IRA—both allow high contribution limits and flexible income deferral.
🔹 Is it too late to reduce 2025 taxes?
Not yet. You can still fund IRAs, make year-end donations, defer income, or harvest losses before December 31, 2025.
9. 🧠 Final Takeaway: Tax Smarter, Not Harder
US taxes are complex—but the 2025 landscape offers huge opportunities for savings. Whether you’re a worker, retiree, investor, or business owner, proactive planning is key to minimizing taxes and maximizing returns.
🧾 Tax is inevitable—overpaying is not.
Stay informed, stay prepared, and always consult a CPA for tailored strategies.
🔍 Sources
IRS | Tax Foundation | Bankrate | KPMG | Tax Policy Center
Disclaimer by Smart Paisa Bharat:
This article offers a directional lens into the evolving US tax framework for 2025. It is not a financial commandment, but a curated guide grounded in current regulations. Tax codes adapt, personal circumstances vary, and the IRS is never one-size-fits-all. When the stakes are real — filings, audits, legacy planning — expert counsel is irreplaceable. Think of this as strategy fuel, not legal finality.